
The bottom line: Several online car buyers are built to buy a car you still owe money on. They contact your lender directly, pay off the balance, and send you whatever is left.
Most private buyers and dealerships won’t go near it, because your lender holds the title until the loan is paid off. For a private sale, Autotrader handles the loan payoff.
All 8 buyers we tested accepted financed cars, but they differ in how long they take to pay off your lender and how much they offer. Some ask for your loan details upfront, and others after you accept.
The winner changed with the car, so compare offers from at least 2 to 3 buyers with Sell Car Advisor before deciding.

Selling a financed car from home
Instant offer, drop-off or pickup
-
Offer amount 35% 5/5
-
Process ease 20% 5/5
-
Offer validity 15% 4/5
-
Pickup / drop-off 15% 4/5
-
Payment speed 15% 4/5
How it works and what it costs
How you sell
- Asks for your lender and balance during the quote
- Pays your lender, which can take several days to clear
- Drop the car off, or book a pickup
Cost to you
- A pickup can carry a fee, shown before you book
- Negative equity is paid upfront by certified check
Watch out for
- Offer holds only seven days
- Keep making loan payments until the payoff clears

A benchmark offer
Instant offer, drop-off or home inspection
-
Offer amount 35% 4/5
-
Process ease 20% 4/5
-
Offer validity 15% 3/5
-
Pickup / drop-off 15% 4/5
-
Payment speed 15% 4/5
How it works and what it costs
How you sell
- Offer on screen in seconds from basic car details
- Inspection at a drop-off site, or an inspector comes to you
- Works with over 100 lenders to pay off your loan
Cost to you
- Inspection, title work and pickup are listed as free
Watch out for
- Offer holds 48 hours and can drop at inspection
- Ask about any title fee before you sign

A quote that holds a month
Online quote, sell at a local location
-
Offer amount 35% 5/5
-
Process ease 20% 3/5
-
Offer validity 15% 5/5
-
Pickup / drop-off 15% 1/5
-
Payment speed 15% 4/5
How it works and what it costs
How you sell
- A person sends the quote, valid for a month
- Drive to a local location for a 30-minute inspection
- Pays your lender and you get any equity, often same day
Cost to you
- Free to use, but you drive there yourself
- Any loan shortfall is paid by you at the sale
Watch out for
- Only 29 locations, 12 of them in Texas
- The final offer can drop after the inspection

A no-haggle price
Online offer, picks up
-
Offer amount 35% 5/5
-
Process ease 20% 3/5
-
Offer validity 15% 4/5
-
Pickup / drop-off 15% 5/5
-
Payment speed 15% 5/5
How it works and what it costs
How you sell
- Offer online, with a question about your loan
- Free pickup from you, in every state
- Pays your lender within 3 to 5 days of pickup
Cost to you
- Free, with no fees published
- Owe more than the offer, and you pay the gap in cash
Watch out for
- Offer holds 7 days and can change after its checks
- May turn down cars over 20 years old or with high miles

High-value cars
Dealer offers
-
Offer amount 35% 4/5
-
Process ease 20% 3/5
-
Offer validity 15% 3/5
-
Pickup / drop-off 15% 4/5
-
Payment speed 15% 4/5
How it works and what it costs
How you sell
- Local dealers make offers on your car
- Drive it to the dealer whose offer you take
- The dealer guides you through the loan payoff
Cost to you
- Free to get offers
- Your drive to the dealer you choose
Watch out for
- Made no offer on the Tesla Model 3 we tested
- The offer ends after 7 days or 250 more miles

Same-day payment at a branch
Estimate online, offer at a branch
-
Offer amount 35% 4/5
-
Process ease 20% 3/5
-
Offer validity 15% 4/5
-
Pickup / drop-off 15% 3/5
-
Payment speed 15% 4/5
How it works and what it costs
How you sell
- Online estimate, a 7-day offer if your car qualifies
- Bring a 10-day payoff letter to the branch inspection
- Equity paid that day, your lender within 3 to 4 business days
Cost to you
- A paperwork fee, such as titling, can apply
- A small fee for an electronic transfer
Watch out for
- The offer can change after the in-person inspection
- Only 86 branches, all in 12 states

Selling in person
Online offer, store or pickup
-
Offer amount 35% 3/5
-
Process ease 20% 3/5
-
Offer validity 15% 4/5
-
Pickup / drop-off 15% 4/5
-
Payment speed 15% 2/5
How it works and what it costs
How you sell
- Firm offer online in minutes, good for 7 days
- CarMax contacts your lender and handles the payoff
- Paid the same day by bank draft, a check you deposit
Cost to you
- A home pickup can carry a fee
- You pay CarMax anything you owe over the offer
Watch out for
- Offered less than most buyers on all three test cars
- The offer can drop if the car doesn't match your answers

Appraisals at several stores
Online offer, sell at a store
-
Offer amount 35% 3/5
-
Process ease 20% 2/5
-
Offer validity 15% 2/5
-
Pickup / drop-off 15% 1/5
-
Payment speed 15% 4/5
How it works and what it costs
How you sell
- Certified offer online, within 30 minutes in business hours
- Drive it to one of over 250 stores
- Loan payoff comes off the offer; the rest by check or Zelle
Cost to you
- Free to sell, with no purchase needed
- Anything you owe over the offer is yours to pay
Watch out for
- Offered less than most buyers on two of three test cars
- The offer ends after 7 days or 500 more miles

A private sale with a loan
Private listing, buyers checked
-
Buyer reach 25% 4/5
-
Safety features 25% 5/5
-
Listing cost 20% 2/5
-
Time to sell 15% 3/5
-
Ease of listing 15% 3/5
How it works and what it costs
How you sell
- You list the car, and Autotrader checks each buyer's identity
- The buyer pays through its checkout, Private Seller Exchange
- Your loan is paid off from the sale at closing
Cost to you
- An ad at $9, $29 or $49, set by your asking price
- Plus 0.99% of the sale, $99 at the least
Watch out for
- Owe more than the sale price, and you pay the gap
- You pay twice: for the ad and on the sale

Automated assistant: general info, not legal advice
Answers come from our state paperwork data and published guides. Confirm anything binding with your state DMV.
Compare Instant Offers
Best Places to Sell a Financed Car
Best For Fully Online Payoffs: Carvana
Carvana buys newer running cars, with pickup in some areas
- Accepts cars with active loans
- Trade-in can save on sales tax
- License plate starts the quote
- Direct deposit option available
-
Offer amount 35% 5/5
-
Process ease 20% 5/5
-
Offer validity 15% 4/5
-
Pickup / drop-off 15% 4/5
-
Payment speed 15% 4/5
Our take on Carvana: Carvana collects your loan details during the quote itself. You enter your lender, remaining balance, and monthly payment before you see an offer. That means the price you get already accounts for your specific payoff situation.
They handle everything from there, and you drop the car off free or book a home pickup where it’s offered, which may cost a fee. The loan payoff adds just a few extra days to the timeline, one of the fastest of any buyer we tested.
Pros
- Collects your loan details upfront, so the offer you see already reflects your lien balance
- Fully online with home pickup. No dealership visit while your lender still holds the title
- Loan payoff adds just a few extra days, one of the fastest timelines on this list
Cons
- Quotes expire in 7 days, which is short if you’re still comparing offers while your lender processes paperwork
- Pickup fees, $0 to $600 in our test offers, can reduce what you net after the loan payoff
- Salvage-title cars are outside its market, so its loan payoff doesn’t help with one
Why we picked it: Carvana integrates your loan info into the quote process itself, so you see your payoff against the offer before you accept, though you still owe Carvana any shortfall if your lender’s final payoff comes in higher. They gave instant offers on all 3 vehicles we tested, including $14,200 on the Tesla and $22,000 on the F-150. For sellers who want to close a financed car sale from home without coordinating between their lender and a buyer separately, this is the most complete option.
How Carvana asks about your loan in their quote form:

Best For Highest Offers: CarBuyerUSA
CarBuyerUSA gives you a quote without asking for your email or phone
- Quote without giving contact info
- Buys cars with frame damage
- Pays storage to release impounded cars
- Agents help with lost titles
-
Offer amount 35% 4/5
-
Process ease 20% 4/5
-
Offer validity 15% 3/5
-
Pickup / drop-off 15% 4/5
-
Payment speed 15% 4/5
Our take on CarBuyerUSA: CarBuyerUSA works with over 100 lenders to handle loan payoffs as part of the sale. Your share of the price arrives after your lender releases the title, and some banks take up to four weeks. They don’t ask about your loan during the quote, but their team confirms the payoff details after you accept. Their first offer led our test on the RAV4 Prime. Some Trustpilot reviewers report the final offer dropping after inspection, and there is a $199 title administration fee at closing that isn’t always mentioned early in the process.
Pros
- Works with over 100 lenders, so most loan types and banks are covered for payoff
- Made the highest single offer in the whole test, on the RAV4 Prime
- Over 400 partner inspection locations across all 50 states
Cons
- Doesn’t ask about your loan during the quote, so the first offer doesn’t reflect your actual equity
- $199 title administration fee at closing reduces your net payout after the loan is paid off
- Some reviewers report the final offer dropping a lot after the in-person inspection
Why we picked it: CarBuyerUSA’s network of over 100 lenders means most financed car situations are covered, including less common loan types. Their first offer was the highest in our entire test set on the RAV4 Prime. Best used as a benchmark. Get their quote early and compare it to Carvana and Driveo to see who actually delivers that number at the inspection stage.
What CarBuyerUSA says about selling with a loan:

Best For Longest Quote Validity: Driveo
Driveo buys at its drop-off locations and pays at the visit
- Quote valid for a month
- Drive the car to a drop-off location
- Paid at the visit
- Free local ride after the sale
-
Offer amount 35% 5/5
-
Process ease 20% 3/5
-
Offer validity 15% 5/5
-
Pickup / drop-off 15% 1/5
-
Payment speed 15% 4/5
Our take on Driveo: Driveo doesn’t ask about your loan during the online quote, but they handle loan payoffs and negative equity at their locations. You bring your most recent loan statement when you drive in. Their 30-day quote validity is the longest of any buyer we tested, a real advantage when you’re waiting on a payoff letter from your lender and don’t want to rush. In our tests they offered $13,650 on the Tesla, $22,550 on the F-150, and $25,150 on the RAV4.
Pros
- 30-day quote window gives you time to get a payoff letter before the quote runs out
- Free Uber or Lyft ride home, which is useful since you can’t drive away once you’ve signed over a financed car
- They explain exactly how they calculated your offer, so you know what the loan payoff deducted
Cons
- Only 29 locations across 13 states. You must drive there, which means arranging a ride home after the title is signed over
- The quote is not instant. A person reviews your details and responds, usually within the hour
- Final offer sometimes comes in lower than the online quote after the in-person inspection
Why we picked it: Driveo’s 30-day quote window is especially valuable for financed car sellers who need time to request a payoff letter from their lender. Payoff amounts change daily as interest accrues, so having a month to sort the paperwork is a real edge, even though the offer is about 3% lower after the first 10 days or so. They finished in the top four of eight on all three vehicles we tested, making them consistently competitive across different car types.
What Driveo says about selling with a loan:

Best For Selling From Home: Driveway
Driveway buys cars online, collects them and pays into your bank
- Offer valid for 7 days
- Photo inspection on your phone
- Paid by bank transfer after pickup
- Picks up anywhere in the U.S.
-
Offer amount 35% 5/5
-
Process ease 20% 3/5
-
Offer validity 15% 4/5
-
Pickup / drop-off 15% 5/5
-
Payment speed 15% 5/5
Our take on Driveway: Driveway includes a loan/lease selection step in their quote form where you choose your finance type and enter your account details. They pay your lender first, then send you what’s left by bank transfer or check. Driveway’s quote holds for 7 days, pending your loan payoff details, but some sellers say it cut the price at pickup or turned the car down. Driveway’s payment to your lender goes out within 3 to 5 days of pickup, so keep up the loan payments until your lender confirms the payoff. Some sellers report document submission issues along the way.
Pros
- The quote form includes a loan/lease field, so your offer accounts for your lien situation before you agree
- Pays what’s left by bank transfer, or by check, once the lender payoff clears
- Free home pickup nationwide, useful when the title is still held by your lender
Cons
- Some sellers have to re-submit loan documents
- Won’t buy cars older than 20 years or with more than 180,000 miles, so the loan payoff option depends on your vehicle qualifying
- Passes on cars with major damage history or title problems, even if the loan could be paid off
Why we picked it: Driveway’s loan integration in the quote form means the price you see is built around your financing situation from the start. They gave the strongest offer on the F-150 among fully online buyers and came in second on the RAV4. Their 7-day quote gives you a number to plan around, but have your lender’s payoff details ready first: a seller’s quote ran out while they waited for a lien release, and others say Driveway cut the price at pickup.
How Driveway asks about your loan in their quote form:

Best For High-Value Vehicles: CarGurus
CarGurus compares instant offers from local dealers side by side
- Offers compared side by side
- Star ratings for each dealer
- Handles your outstanding loans
- Dealer pays by check or transfer
-
Offer amount 35% 4/5
-
Process ease 20% 3/5
-
Offer validity 15% 3/5
-
Pickup / drop-off 15% 4/5
-
Payment speed 15% 4/5
Our take on CarGurus: CarGurus asks about your ownership status during the quote process. You select “Financed” and see offers from local dealers, since CarGurus doesn’t buy cars itself. The dealer that buys the car handles the paperwork with your lender. If you owe more than the dealer pays, you cover the difference.
CarGurus’ $24,500 led the offers on the F-150. But they made no offer on the Tesla Model 3, which shows their coverage depends heavily on vehicle demand in your area.
Pros
- The quote flow includes a “Financed” ownership option, so they’re designed to handle loans from the start
- Dealer competition on certain vehicles can push offers higher than purely online buyers
- The buying dealer guides you through settling the loan as part of the sale
Cons
- No offer was generated for the Tesla Model 3. Financed cars that aren’t in high demand may not get quotes
- Dealer figures are estimates, not locked prices. The final number is set when you visit the dealership
- Offer expires in 7 days or 250 additional miles, which is tight when coordinating a lender payoff
Why we picked it: CarGurus produced the highest single offer of any buyer we tested on the F-150. For financed trucks and SUVs in strong demand, their dealer network creates real price competition. Worth checking if you have a popular vehicle. Just plan to drive the car to the dealer, and know that the dealer can lower the offer once it inspects the car.
How CarGurus asks about your loan in their quote form:

Best For Same-Day Branch Payment: We Buy Any Car USA
WeBuyAnyCarUSA buys cars face-to-face at their branches
- Appraisal at a branch or at home
- Check handed over on the spot
- Paid same day by Zelle, ACH or check
- Mobile appraiser comes to you
-
Offer amount 35% 4/5
-
Process ease 20% 3/5
-
Offer validity 15% 4/5
-
Pickup / drop-off 15% 3/5
-
Payment speed 15% 4/5
Our take on We Buy Any Car USA: We Buy Any Car USA handles financed cars at their branches and through mobile service. They don’t ask about your loan during the online quote, but you bring a current payoff letter from your lender to the appointment. They pay off the loan out of the sale and pay you the difference the same day, by company check, Zelle or bank transfer.
Their 86 branches are all in 12 states. In our tests they were competitive but not the highest on any vehicle.
Pros
- 86 branches plus mobile service. Loan payoff handled face-to-face with same-day payment
- Company check can be cashed immediately at any Truist Bank location, no waiting for a bank hold
- They explain the full price breakdown, so you know exactly what the lender took and what you keep
Cons
- Requires a current payoff letter from your lender before your appointment, so add 1 to 2 days to your prep time
- Online quotes can drop at the in-person inspection, which matters more when your loan equity is thin
- Some sellers report small hidden paperwork fees that weren’t disclosed upfront
Why we picked it: We Buy Any Car USA is the best option when you want the loan payoff handled in person and you need to leave with a check the same day. Their branch model and Truist Bank cashing option solves the bank-hold problem that comes with large checks after a lender payoff. Just get the payoff letter from your lender first and come in ready to negotiate if the final offer drops.
What WeBuyAnyCar says about selling with a loan:

Best For In-Person Convenience: CarMax
CarMax inspects and buys your car at 250+ stores
- Buys your car even if you don't buy one there
- Offer holds seven days and is not negotiable
- At-home pickup, though not everywhere and a fee may apply
- Quote in about 2 minutes online
-
Offer amount 35% 3/5
-
Process ease 20% 3/5
-
Offer validity 15% 4/5
-
Pickup / drop-off 15% 4/5
-
Payment speed 15% 2/5
Our take on CarMax: CarMax is the easiest to reach with over 250 locations and at-home pickup now available in most markets. They don’t ask about your loan during the online quote but handle financed cars at the inspection stage. CarMax pays your lender after the sale, and some of its sellers waited three to seven weeks for that money to arrive, so keep making your monthly payments until your lender confirms the payoff or it can affect your credit. In our tests, CarMax made the lowest offer on the RAV4 Prime and the second lowest on the Tesla Model 3 and the F-150.
Pros
- Over 250 stores plus at-home pickup. The most accessible option for financed car sellers across the country
- Same-day payment when you accept, even for financed cars. You don’t have to wait for the lender payoff to finish to get paid
- Offer Watch tool lets you track your car’s value and pick the best window to sell before committing to a quote
Cons
- Some sellers’ loan payoffs took three to seven weeks to reach the lender. You must keep making monthly payments during that window or it can damage your credit
- Offered less than most other buyers on all three vehicles in our tests
- Payment by check only, which can take 5 to 10 business days to clear at your bank
Why we picked it: CarMax earns its spot for reach and process reliability, not for offer amounts. If every other buyer has turned down your financed car or you’re in an area with limited options, CarMax is a dependable fallback. Just know that the payoff can take weeks to reach your lender, so plan your loan payments around it.
What CarMax says about selling with a loan:

Best For Multiple Store Access: AutoNation
AutoNation's 250+ dealerships buy cars outright or as trade-ins
- Sell at any of 250+ locations
- Offer good for 7 days or 500 miles
- Compare offers across nearby stores
- Buys economy to luxury vehicles
-
Offer amount 35% 3/5
-
Process ease 20% 2/5
-
Offer validity 15% 2/5
-
Pickup / drop-off 15% 1/5
-
Payment speed 15% 4/5
Our take on AutoNation: AutoNation works directly with your lender on financed cars, but it gives no time for the payoff to go through. During that period, you need to keep making your monthly payments. Its offer can expire before 7 days, and ours expired in 3, which is tight when you’re coordinating a loan payoff. In our tests they offered less than most other buyers on two out of three vehicles.
Pros
- More than 250 locations. If you’re in a big city, you can get competing appraisals from multiple AutoNation stores on the same day
- Publicly traded company that pays your lender directly
- Handles financed cars and works directly with your lender. No coordination required from you after the sale
Cons
- Offers hold 7 days at most, which is tight when you need time to gather lender payoff paperwork
- Offered less than most other buyers on 2 out of 3 vehicles in our tests
Why we picked it: AutoNation’s 250-plus stores create a real option for sellers in major cities who want to pit multiple locations against each other on the same day. For financed cars with positive equity, AutoNation pays the lender itself, though some sellers had to chase a payoff that was overstated or came up short. Just plan around its short quote window. Gather your payoff letter from your lender before you even get the online quote.
What AutoNation says about loan payoff:

Other Options For Selling a Financed Car
Selling privately usually gets you more money than selling to a company. But most private sale platforms don’t help with loan payoffs, which makes financed car private sales complicated. There’s one exception.
Best For Private Sale Payoff Support: Autotrader
Autotrader's exchange takes the buyer's payment and does the title paperwork
- Buyer pays through PSX, not cash
- Free AutoCheck report on every ad
- Ad shows on Autotrader and KBB.com
- Title paperwork and payoff handled
-
Buyer reach 25% 4/5
-
Safety features 25% 5/5
-
Listing cost 20% 2/5
-
Time to sell 15% 3/5
-
Ease of listing 15% 3/5
Our take on Autotrader: Autotrader runs a Private Seller Exchange that connects you with individual buyers, not dealers. If you have a loan, Autotrader works directly with your lender to pay off the balance from the sale proceeds and gets the title released before transferring it to the buyer. Every buyer must pass an ID check before paying, and payments go through Autotrader’s system, which matters when a private buyer knows your car is still financed and you need protection from fake payment attempts.
The cost is $9, $29 or $49 to list, depending on your asking price, plus 0.99% of the sale price at closing (minimum $99). Facebook Marketplace is free and Craigslist charges $5 to list a car, but neither handles the loan payoff. You’d have to coordinate with your lender and the buyer yourself, which most buyers won’t want to deal with.
If the extra money from a private sale is worth it to you, Autotrader’s Private Seller Exchange handles a financed car sale from the listing through the loan payoff and title. Use KeySavvy as an alternative if you want similar payment protection at a lower fee.
Best Places to Sell a Financed Car: What Each Buyer Offered
We submitted each of the 3 vehicles to all 8 buyers using the same Florida zip code. Here’s every offer we received.
All Offers at a Glance
| Vehicle | |
|
|
|
|
|
|
|
|---|---|---|---|---|---|---|---|---|
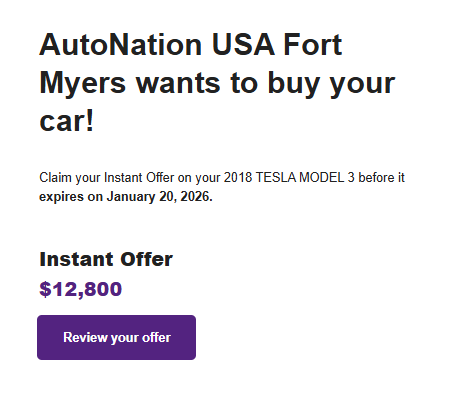
| 2018 Tesla Model 3 | $14,200 | $13,761 | $13,650 | $11,000 | No offer | $12,076 | $11,400 | $12,800 |
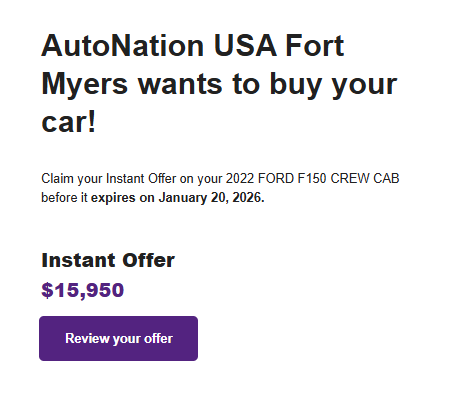
| 2022 Ford F-150 XL | $22,000 | $22,890 | $22,550 | $23,450 | $24,500 | $21,501 | $18,400 | $15,950 |
| 2021 Toyota RAV4 Prime SE | $24,600 | $25,920 | $25,150 | $25,650 | $25,700 | $24,441 | $22,400 | $23,700 |
2018 Tesla Model 3
2022 Ford F-150 XL
2021 Toyota RAV4 Prime
2018 Tesla Model 3
73,000 miles · Clean title


| $14,200 |
|
| $13,761 |
|
| $13,650 |
|
| $12,800 |
|
| $12,076 |
|
| $11,400 |
|
| $11,000 |
|
| No offer |
2022 Ford F-150 XL
72,500 miles · Clean title


|
| $24,500 |
|
| $23,450 |
|
| $22,890 |
|
| $22,550 |
| $22,000 |
|
| $21,501 |
|
| $18,400 |
|
| $15,950 |
2021 Toyota RAV4 Prime SE
61,505 miles · Clean title


|
| $25,920 |
|
| $25,700 |
|
| $25,650 |
|
| $25,150 |
| $24,600 |
|
| $24,441 |
|
| $23,700 |
|
| $22,400 |
We got these quotes with a Florida ZIP code. Your offers can be higher or lower, because they depend on where you live, your car’s condition and what buyers need in your area.
What This Tells Us
What this tells us:
- Every buyer on this list accepts financed cars. The differences are entirely in process: how quickly they pay the lender, whether they ask about your loan upfront, and how long you need to keep making monthly payments.
- Buyers that collect loan details during the quote tend to give more stable first offers. Buyers that calculate the payoff after you accept are more likely to adjust the number when they work out the actual equity.
- The payoff timeline ranged from a few extra days to several weeks. For a car with thin equity, extra monthly payments during that window directly reduce what you walk away with.
- Fully online buyers consistently offered more than dealers in our tests. The dealership inspection stage is where offers tend to drop, and it doesn’t exist in a fully online sale.
- A 30-day quote validity window matters specifically for financed car sellers. Lender payoff letters take time to get, the amounts change daily with interest, and having a month to sort it without losing your quote is a meaningful advantage.
- Your exact payoff amount is as important as your car’s value. Get a payoff quote from your lender before collecting buyer quotes. Your real payout is the gap between those two numbers.
- Private sale platforms can get you more money, but most won’t touch the loan payoff process. The only platform that handles it end-to-end comes with listing and closing fees that cut into your extra profit.
- Offer gaps between buyers were wider on higher-value vehicles. On the F-150, the spread from highest to lowest was bigger than on either other vehicle, which means the loan status didn’t flatten the market the way it might on a cheaper car.
To see what different buyers offer for your financed car, get quotes from several at once:
Compare instant offers before you accept one
Compare instant offers before you accept one
Frequently Asked Questions
Can I sell a financed car without paying off the loan first?
Yes. All 8 buyers on this list handle the loan payoff for you. They contact your lender directly, pay off the balance, and send you the difference.
You’ll need your loan account number and current payoff amount ready. Some buyers complete the payoff in a few days. Others take several weeks.
What happens if I owe more than the car is worth?
This is called negative equity or being upside down on your loan. Edmunds puts the share of trade-ins toward a new car that carried negative equity at 29.6%, and those underwater cars averaged 4.0 years old. You’ll need to pay the difference between what the buyer offers and what you still owe.
For example, if Carvana offers $14,200 and you owe $16,000, you’d need to bring $1,800 to close the sale. Every buyer on this list requires you to cover that gap.
Which company offers the most for financed cars?
It depends on the vehicle. In our tests, CarBuyerUSA offered the most for the 2021 RAV4 Prime. CarGurus offered the most for the 2022 F-150. Carvana offered the most for the 2018 Tesla Model 3.
No single buyer wins every time. Getting quotes from at least 3 services before deciding is the only way to know who will offer the most for your specific car.
How long does it take to sell a financed car?
Longer than selling a car you own outright. The loan payoff adds anywhere from a few extra days to several weeks depending on which buyer you use.
Carvana and Driveo are among the fastest at just a few extra days. At CarMax, some sellers’ payoffs took three to seven weeks to reach the lender.
Do I need to keep making loan payments while selling?
Yes. Keep making your monthly payments until the loan shows as fully paid off with your lender. Stopping too early can hurt your credit score.
This matters most with buyers that have long payoff timelines. If your buyer’s payoff takes weeks, as some CarMax sellers’ did, you may need to make one or two more payments before the account closes.
What documents do I need to sell a financed car?
Most buyers need your loan account number, current payoff amount, lender contact info, a valid ID, and your car’s registration.
Some also ask for a recent payoff letter from your lender before or at the appointment.
Call your lender before you start to get your exact payoff amount. This number changes daily because of interest accruing on the balance.
Can I sell a leased car to these companies?
Some of them, yes. Carvana and Driveway have lease fields in their quote forms; Carvana buys out leases only from 13 approved leasing companies, and with any other you pay off the lease and retitle the car first.
You’ll need your buyout amount and whether your leasing company allows third-party sales.
Not all leasing companies allow you to sell to a third party. Check your lease agreement or call them before getting quotes.
Can I sell a financed car privately?
You can list a financed car on Facebook Marketplace or Craigslist, but neither platform helps with the loan payoff.
You’d need to coordinate with your lender and the buyer yourself, which most private buyers won’t want to deal with.
Autotrader’s Private Seller Exchange lists your car and pays off your loan from the sale money, so the buyer gets a clear title. It costs more in fees but solves the title problem that makes financed car private sales so difficult.
Is it better to sell a financed car online or at a dealership?
Online buyers offered more than in-person dealers in our tests across all three vehicles. The dealership model adds an in-person appraisal, where the online quote can drop.
Dealer options like CarMax and AutoNation are more familiar and reliable if you want to handle everything face-to-face.
But if maximizing the payout on your financed car matters more, start with the fully online buyers and compare.
Methodology
We selected 3 vehicles with clean titles that represent common financed car situations: a 2018 Tesla Model 3 (73,000 miles), a 2022 Ford F-150 XL (72,500 miles), and a 2021 Toyota RAV4 Prime SE (61,505 miles). All three were newer enough to attract multiple buyers and varied enough in type to show how offers differ by vehicle.
We submitted each vehicle to all 8 buyers using the same Florida zip code and answered all condition questions accurately. We took screenshots of every result. We also reviewed how each company presents their loan payoff process on their website to understand what sellers can expect before and after they accept.
CarGurus gave instant quotes on 2 out of 3 vehicles but made no offer on the Tesla Model 3. All other buyers quoted every vehicle, and all but Driveo did it instantly.
We did not accept any offers. Your results may differ based on your location, vehicle condition, and which buyers are active in your area at the you sell your car.
Article Update History
Originally posted and shared with our readers.

Sources
"29.6%, underwater trade-ins; 4.0 years, age of a car traded in underwater" Accessed Sep. 21, 2026
Found this useful? Show Sell Car Advisor first when you search on Google.
Add us as a preferred source on Google